The Psychology of Why Smart People Make Terrible Financial Decisions
Intelligence does not shield investors from overconfidence, loss aversion, and herd behavior, but a few simple safeguards can protect their returns.
Smart people make terrible financial decisions because intelligence does not remove emotional and cognitive biases; it often supplies better arguments for acting on them.
Overconfidence, loss aversion, and herd behavior affect high achievers as much as anyone, and expertise can widen the gap between what investors believe they know and what they can control.
Trending Now!!:
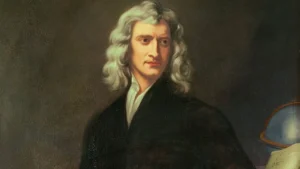
The pattern appears in some of the best-documented episodes in the history of money. Isaac Newton, who ran the Royal Mint, lost a fortune in the South Sea Bubble.
A hedge fund built around two Nobel laureates, Myron Scholes and Robert Merton, needed a $3.6 billion rescue organized by the Federal Reserve Bank of New York. Ignorance explains neither case. Both failures came from people who understood the mechanics and still misjudged themselves.
Readers who search this topic usually want something practical: why capable people keep losing money, how much it costs, and what actually prevents it. The evidence points to a small set of mechanisms and an even smaller set of fixes that work without relying on willpower.
Why Intelligence Does Not Protect Against Money Mistakes
Financial decisions combine uncertainty, emotion, and delayed feedback, three conditions under which raw cognitive ability helps less than most people assume.
A surgeon, engineer, or litigator spends a career in domains where skill produces visible results and mistakes are corrected quickly. Markets offer none of this. A reckless decision can look brilliant for years, and a sound one can look foolish for just as long.
Research on the bias blind spot adds a second problem: higher cognitive ability does not reliably make people better at detecting their own biases. Smart people are often better at building a persuasive case, which makes motivated reasoning more effective, not less.
An investor who wants to keep a falling stock can produce a detailed thesis for doing so. A less sophisticated investor might simply admit the position is a loss.
Overconfidence and the Price of Trading Too Much
The most measurable cost of overconfidence is excessive trading. Brad Barber and Terrance Odean studied the accounts of more than 35,000 households at a large discount brokerage from 1991 to 1997 and found that trading reduced net returns for nearly everyone. Their paper “Trading Is Hazardous to Your Wealth” became a landmark in behavioral finance for that reason.
A follow-up study used gender as a proxy for overconfidence, based on psychological research linking the trait to men in financial settings. Men traded 45 percent more than women, and trading cut men’s net returns by 2.65 percentage points a year against 1.72 for women.
Single men traded 67 percent more than single women. The finding has limits: later research on other datasets questioned how neatly gender maps to overconfidence, and some work suggests the type of trading platform matters as much.
The core result still holds across much of the literature, which is that more activity tends to mean lower net returns once costs and poor timing are counted.
High achievers carry a specific version of this risk. Success in one field breeds the belief that judgment transfers to another. A physician who diagnoses accurately under pressure may assume the same instincts apply to sector rotation, options strategies, or a private deal offered by a friend.
Loss Aversion and the Reluctance to Sell Losers
Daniel Kahneman and Amos Tversky introduced prospect theory in 1979, and the idea at its center is loss aversion: a loss hurts more than an equal gain pleases, with estimates of the ratio typically falling between 2 and 2.5 to one.
Kahneman received the 2002 Nobel Prize in economics for the work; Tversky had died in 1996 and could not share it.
In practice, loss aversion produces the disposition effect, the tendency to sell winners too early and hold losers too long. Odean documented the pattern in a study of individual investor accounts titled “Are Investors Reluctant to Realize Their Losses?”
Selling a loser makes the loss real, so the investor holds on, often in the hope of getting back to even. The purchase price becomes an anchor that has no bearing on the stock’s future.
Awareness does not fix it. Kahneman observed that public knowledge of loss aversion grew after the research appeared, while the bias itself did not shrink. Among intelligent investors, the usual symptom is rationalization: the position becomes a long-term hold, the thesis remains intact, and the loss is described as temporary.
When Sophistication Becomes the Risk Factor
Long-Term Capital Management shows how expertise can amplify error. The fund was founded in 1994 by John Meriwether, and its board included Scholes and Merton, who shared the 1997 Nobel Prize in economics for work on option pricing.
Its strategy depended on small price differences between related securities, which meant that meaningful profits required heavy leverage.
At the start of 1998, equity stood near $5 billion against more than $125 billion in borrowed assets, a ratio of roughly 25 to 30 times.
The fund returned about $2.7 billion to outside investors in late 1997, which pushed leverage higher. Risk models calibrated to historical volatility treated the Russian default and the resulting flight to safety as unlikely. In less than four months, the fund lost about $4.6 billion, and 14 banks put up $3.6 billion to prevent a disorderly liquidation.
The lesson reaches well beyond hedge funds. Diversification proved illusory because many positions amounted to the same bet. The models were internally consistent but rested on assumptions that failed under stress.
Retail investors repeat the pattern at a smaller scale with margin loans, leveraged ETFs, and concentrated positions built on a tidy spreadsheet and one unexamined assumption.
Herd Behavior and the Newton Problem
Newton made the right call first. He sold his South Sea shares at a profit, then watched acquaintances grow rich as the price kept climbing, and bought back in near the top.
The loss is commonly put at about £20,000, a sum far beyond an ordinary worker’s lifetime earnings in that era.
The famous line attributed to him, “I can calculate the motion of heavenly bodies, but not the madness of people,” may be apocryphal: the earliest record appears in a notebook from 1756, decades after his death, as a secondhand recollection. The financial history is on firmer ground.
The mistake was social, not mathematical. Regret over missing gains and the discomfort of watching peers profit pushed a brilliant man to abandon a sound decision.
Modern equivalents appear in every speculative cycle, from technology stocks to meme stocks to cryptocurrency. Fear of missing out is not a symptom of low intelligence; it is a response to social comparison that the most analytical people feel as strongly as anyone.
What the Behavior Gap Costs in Real Numbers
Two long-running studies quantify the damage. DALBAR’s annual analysis of investor behavior found that in 2024 the average equity fund investor earned 16.54 percent while the S&P 500 returned 25.02 percent, a gap of 848 basis points and the second largest of the preceding decade.
The following year, the gap narrowed to 72 basis points, with investors earning 17.16 percent against 17.88 percent for the index. The swing shows that the gap is not constant: it widens when markets move fast and emotions run high.
Morningstar’s Mind the Gap research measures dollar-weighted returns against fund returns and finds a smaller but persistent shortfall. Over the ten years ended December 2023, fund investors earned 6.3 percent a year while their funds returned 7.3 percent, a loss of roughly 15 percent of total returns to mistimed purchases and sales.
Investors in allocation funds had the narrowest gap, and the average dollar in index funds earned 7.6 percent a year against 5.5 percent in active funds.
A fair reading requires caution. Some analysts argue that DALBAR’s method can overstate the gap because it treats ordinary contributions and withdrawals as timing decisions. Even the more conservative Morningstar figure matters, because one percentage point compounds.
A $100,000 portfolio growing at 7.3 percent for 30 years reaches roughly $828,000; at 6.3 percent, it reaches roughly $625,000. The difference exceeds $200,000, and it comes entirely from behavior.
A Practical Framework: The Four Locks
Willpower fails under stress, so the most effective safeguards remove decisions from the moment of maximum emotion. A useful structure can be called the Four Locks.
The Default Lock
Automate contributions to retirement accounts and raise them on a schedule. Pair them with a diversified allocation fund or a low-cost index fund so there is no moment of choice to get wrong.
Morningstar’s findings that allocation funds produced the narrowest gaps support the logic: routine and simplicity capture more of the return.
The Rules Lock
Write an investment policy before any crisis: target allocation, rebalancing bands, and a maximum percentage for any single position, including employer stock. A written rule is much harder to argue away than a private intention.
The Delay Lock
Impose a mandatory waiting period for discretionary trades, such as 48 hours for any purchase and 30 days for any sale of a core holding during a market drop. Delay costs little and filters out decisions driven by panic or excitement.
The Second-Opinion Lock
Assign a person the authority to question major moves. A fee-only fiduciary financial advisor is the formal version, and the value lies less in stock selection than in behavioral coaching and a check on impulsive decisions.
Morningstar’s cross-market work suggests that markets with more holistic advice tend to show smaller timing losses. Robo-advisors serve a similar function by automating allocation and rebalancing, though they cannot talk anyone out of a panic.
Advisors also earn their fee by pushing the unglamorous basics that capable people skip: an emergency fund, paying down high-interest debt, and adequate insurance.
The Uncomfortable Conclusion
Intelligence is not a liability in money matters, but it is a poor substitute for structure. The evidence from Newton to LTCM to modern fund flows points the same way: the investors who fare best are rarely the ones who trust their judgment most.
They are the ones who assume their judgment will fail at the worst moment, and who build automatic systems, written rules, and outside checks to limit the damage when it does.
What People Ask