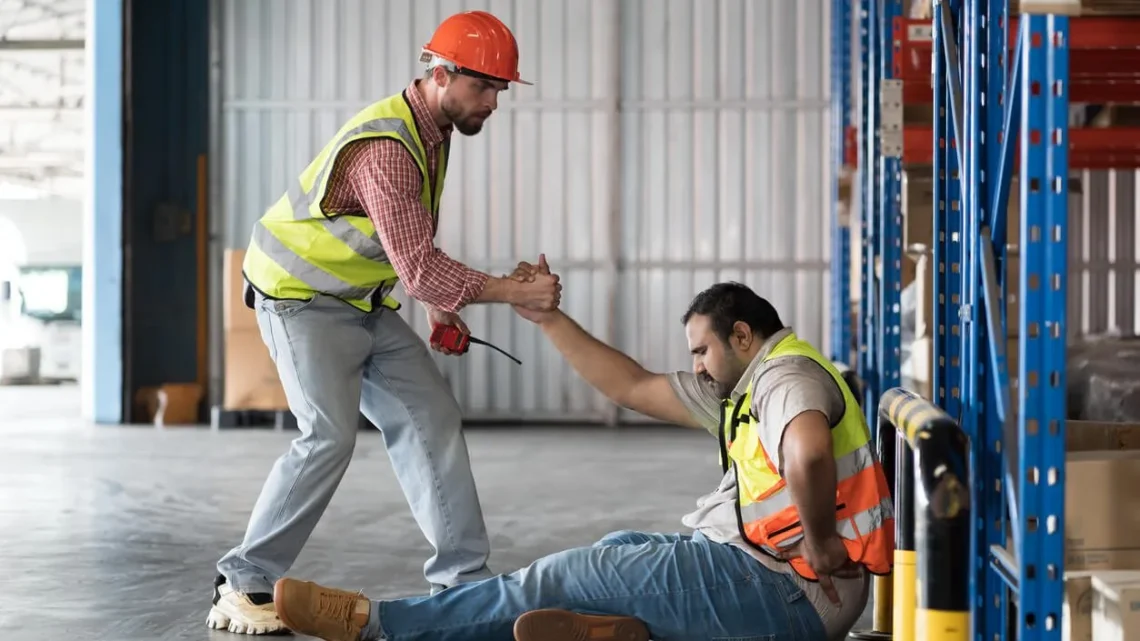
Injured at Work? What You Are Owed
Medical care, weekly wage replacement and awards for lasting impairment are owed in most states, but three overlapping deadlines decide who actually collects.
Private employers reported about 2.5 million nonfatal workplace injuries and illnesses in the latest federal count, and the median case that kept someone off the job lasted eight days.
Eight days feels like a short interruption. It is also long enough to trigger a legal process with deadlines that can end a claim before treatment is finished.
Trending Now!!:
An injured worker is generally owed three things regardless of fault: payment for reasonable medical treatment, partial wage replacement while unable to work, usually about two-thirds of average weekly pay up to a state cap, and compensation for any lasting impairment. Dependents receive death benefits. Formulas and deadlines vary by state.
What Workers’ Compensation Actually Pays
Workers’ compensation is a trade. The worker gives up the right to sue the employer for negligence, and the employer, through an insurer or a self-insured fund, pays set benefits without anyone proving who was at fault.
The test for coverage is whether the injury was “arising out of and in the course of employment”, a phrase that appears in some form in most state statutes.
That test covers more than sudden accidents. Repetitive strain, hearing loss, occupational disease, and the aggravation of a condition that existed before the job can all qualify.
The ordinary commute generally does not, though exceptions exist for errands done for the employer and travel that is part of the job.
Benefits fall into four groups:
- Medical care: Reasonable and necessary treatment for the injury, including doctor visits, surgery, prescriptions, therapy, and devices, typically without deductibles or copays. Many states also reimburse travel to appointments.
- Temporary disability: Wage replacement while a doctor says the worker cannot work (total) or can work only with limits (partial).
- Permanent disability: Compensation when the injury leaves lasting impairment, either partial or total.
- Death benefits: Weekly payments to a surviving spouse and dependents, plus a burial allowance.
Some states add vocational rehabilitation for workers who cannot return to their old trade.
The Math Behind the Weekly Check
Most states pay two-thirds of the worker’s average weekly wage, though the range runs from 60 to 80 percent. The average is usually built from gross earnings in the 52 weeks before the injury. New York counts overtime and other compensation in that figure, and Massachusetts uses the same 52-week window.
Every state then applies a ceiling tied to its statewide average weekly wage. New York caps the benefit at two-thirds of that statewide average.
Massachusetts caps it at the statewide average itself. Higher earners therefore lose a larger share of their real pay, while some states, Pennsylvania among them, pay a higher percentage to the lowest earners.
A hypothetical example shows the arithmetic. A worker averaging $900 a week, overtime included, would typically receive about $600 a week if that sits under the state maximum. Workers’ compensation benefits are generally not subject to federal income tax, so the gap between that check and ordinary take-home pay is narrower than the one-third haircut suggests.
Partial disability uses a different formula. A worker who returns on reduced hours or lower pay can receive roughly two-thirds of the difference between the old average wage and the new earnings. New York’s permanent partial formula multiplies two-thirds of the average weekly wage by the percentage of disability established by medical evidence.
A practical rule of thumb: multiply gross weekly pay, overtime included, by two-thirds, then compare the result with the state maximum on the state agency’s website. Workers with irregular hours should ask how the average was calculated. A figure drawn from a slow stretch understates what the job paid.
The Three Clocks That Decide Whether a Claim Survives
Most lost claims fail on timing rather than merit. Three separate clocks run at once.
The notice clock starts at the injury. States require the worker to tell the employer within a set period, from a few days in some states to 30 days or more in others. Written notice, dated and kept, removes arguments later.
The filing clock governs the formal claim with the state agency. Many states allow two years from the injury, though the period can be shorter for occupational diseases measured from diagnosis or from when the worker should have known the cause.
The appeal clock starts the day a claim or benefit is denied, and it is the shortest of the three. Nevada gives 70 days to appeal a denial. Alaska requires a worker whose claim has been formally contested to request a hearing within two years, and missing that date can end the claim entirely.
Two smaller timers sit inside these. Wage benefits usually begin only after a waiting period of three to seven days. The first days are paid retroactively once the disability lasts long enough, commonly 14 days, or 21 in Alabama.
Medical care is not subject to that wait in many states. Some insurers also face a decision deadline: in Minnesota, an insurer must decide liability within 14 days when disability runs past three calendar days.
The decision rule: treat the shortest plausible deadline as the real one, report in writing immediately, and calendar the appeal window the day any denial letter arrives.
Medical Care and the Question of Who Chooses the Doctor
Medical rules differ sharply by state. In many states, the employer or insurer picks the first doctor or supplies a list. Others let the worker choose from the start, and some allow one change without permission. Oklahoma, for example, gives the employer the initial choice within five days of learning of the injury.
The practical step is to ask who selects the doctor before the first non-emergency visit. Emergency care never waits for that answer.
The treating physician’s notes matter more than most workers expect. They establish whether the injury is work-related, set work restrictions that drive wage benefits, and eventually produce the impairment rating.
The description of how the injury happened should be complete and consistent from the first appointment. A vague “it just started hurting” can be read later as evidence of a non-work cause.
Running treatment through personal health insurance to avoid friction with the employer usually backfires. The health plan can seek reimbursement, and the paper trail suggests the injury was not work-related. Insurers may also require an independent medical examination, and the rules on second opinions vary by state.
When the Injury Leaves a Permanent Mark
Once a doctor concludes that further treatment will not improve the condition, the worker reaches “maximum medical improvement”. That milestone shifts the claim from temporary to permanent benefits.
Many states use a schedule that assigns a fixed number of weeks of pay to specific losses such as a finger, hand, or eye. Injuries to the back or other parts not on the schedule are usually valued by disability percentage or by actual wage loss.
Permanent total disability, for a worker who cannot return to any gainful work, is paid for a longer period and in some states for life.
This is the most contested part of the system. Long-running research on benefit adequacy has found that permanent partial awards replace much less of lost earnings than the two-thirds standard would suggest, and employer groups dispute that two-thirds is the right benchmark at all.
Lump-sum settlements need particular care. Some settlements close the claim for medical care as well as wages, which leaves the worker paying for future surgery or therapy. A settlement offer is the moment to ask exactly which benefits are being released.
Death benefits follow their own formulas. In Massachusetts, a surviving spouse receives two-thirds of the deceased worker’s average weekly wage, subject to the statewide cap. Other states pay between 50 and two-thirds, and one state caps payments at 500 weeks.
The federal count recorded 5,070 fatal work injuries in its latest year, with roadway incidents the most frequent single event, so these benefits matter well beyond the heavy-industry sectors people tend to picture.
When Someone Other Than the Employer Caused the Injury
Workers’ compensation does not pay for pain and suffering, emotional distress, or punitive damages. For a straightforward workplace accident, that limit is the price of the trade. It does not apply when a separate party caused the harm.
A third-party claim is a regular personal injury lawsuit against someone other than the employer or co-workers: the manufacturer of a defective machine, a negligent driver, a property owner, or a subcontractor from another company on a shared site.
A hypothetical example: a delivery driver injured when another motorist runs a red light can collect workers’ compensation from the employer’s insurer and also sue the motorist.
The second claim has its own consequences. The compensation insurer usually holds a lien on the recovery to repay benefits it paid, and the size and reach of that lien depend on state law.
Massachusetts, for one, bars the lien from attaching to damages for pain and suffering. The lawsuit also runs on a personal injury deadline that is separate from the compensation clock and can be shorter than expected.
The wall against suing the employer is not absolute. Most states recognize an exception for intentional harm, but courts read it narrowly, and ordinary carelessness or even a known safety violation rarely qualifies.
Texas, Contractors, and Other Gaps in Coverage
Texas is the only state where private employers may opt out of workers’ compensation. The Texas Department of Insurance found that 24 percent of private employers were non-subscribers in its latest biennial report, and 13 percent of employees worked for one, the lowest share in a decade.
A non-subscriber can be sued for negligence in court, and many run their own injury benefit plans with terms that differ from the statutory ones.
Other gaps are quieter. Some states exempt or limit coverage for very small employers, certain farm work, and domestic employees. Workers labeled independent contractors are not covered by the employer’s policy, but the label does not settle the question.
States apply tests focused on how much control the business exercises, and a misclassified worker can sometimes establish employee status and claim benefits. Federal employees, railroad workers, and maritime workers sit under separate federal systems with their own rules and forms.
Retaliation, Job Protection, and Returning to Work
Federal law prohibits punishing a worker for reporting a work-related injury or illness. The Occupational Safety and Health Administration handles these complaints under Section 11© of the Occupational Safety and Health Act, and the deadline is 30 calendar days from the retaliatory act. Complaints can be made by phone and in any language.
A complaint filed after 30 days may be referred to the National Labor Relations Board. In states running their own OSHA-approved plans, workers may also file under the state’s equivalent provision.
Time away from work can overlap with other protections. The Family and Medical Leave Act provides up to 12 weeks of job-protected unpaid leave for eligible workers at covered employers, and a work injury can qualify. The Americans with Disabilities Act may require reasonable accommodation when the worker returns.
Return-to-work offers need attention. An employer may offer modified duty that fits the doctor’s restrictions. In many states, refusing a suitable offer can reduce or suspend temporary wage benefits. A worker who believes the duties exceed the restrictions should raise it in writing and ask the doctor to confirm the limits rather than simply declining.
Mistakes That Quietly Shrink Claims
Delay is the most common error. A worker who waits for the pain to prove itself gives the insurer room to argue that the injury happened elsewhere.
The same logic applies to minor incidents: a back twinge reported on the day it happens is far easier to defend than a herniated disc reported three months later.
Informal reporting also fails. A verbal mention to a supervisor feels like notice, but without a written record it can vanish. A short email with the date, the location, and what happened closes that gap.
Other mistakes are quieter:
- Giving a recorded statement to the insurer before understanding the claim.
- Posting activity on social media that contradicts the stated restrictions.
- Skipping medical appointments, which insurers use to argue the injury is not serious.
- Signing a settlement without confirming whether future medical care is included.
When a Claim Is Denied
Denials usually rest on a short list of reasons: late notice, a dispute over whether the injury happened at work, a pre-existing condition, gaps in medical evidence, or a challenge to employee status.
A denial is a starting position, not a verdict, and appeals succeed often enough that most state agencies run formal hearing systems for exactly this purpose.
Nevada’s guidance captures the correct instinct: file the appeal as soon as a benefit is denied, even if more evidence is still needed. Evidence can be added after the deadline-protecting filing is in place, but the deadline cannot be extended after it passes.
Legal help becomes worth considering at a few specific points: a denial, a permanent impairment rating the worker disputes, a settlement offer, or any injury with a possible third-party claim. Attorneys in compensation hearings are typically paid a percentage of the benefits awarded, which keeps upfront cost low.
The First-Week Checklist
- Report the injury to the employer in writing, with the date, time, location, and a plain description of what happened.
- Get medical treatment immediately, ask who selects the doctor for non-emergency care, and state clearly at every appointment that the injury happened at work.
- Keep copies of every form, work-status note, and letter, and log each call with the date and the name of the person spoken to.
- Write down the state’s notice, filing, and appeal deadlines, and treat the shortest as the real one.
- Confirm the weekly benefit by checking the average weekly wage calculation against recent pay stubs, overtime included.
- Hold off on signing statements, releases, or settlement papers until the scope of the medical and wage rights being given up is clear.
What People Ask